21 August 2026
|
5 min read
How to Raise Capital for Your Business

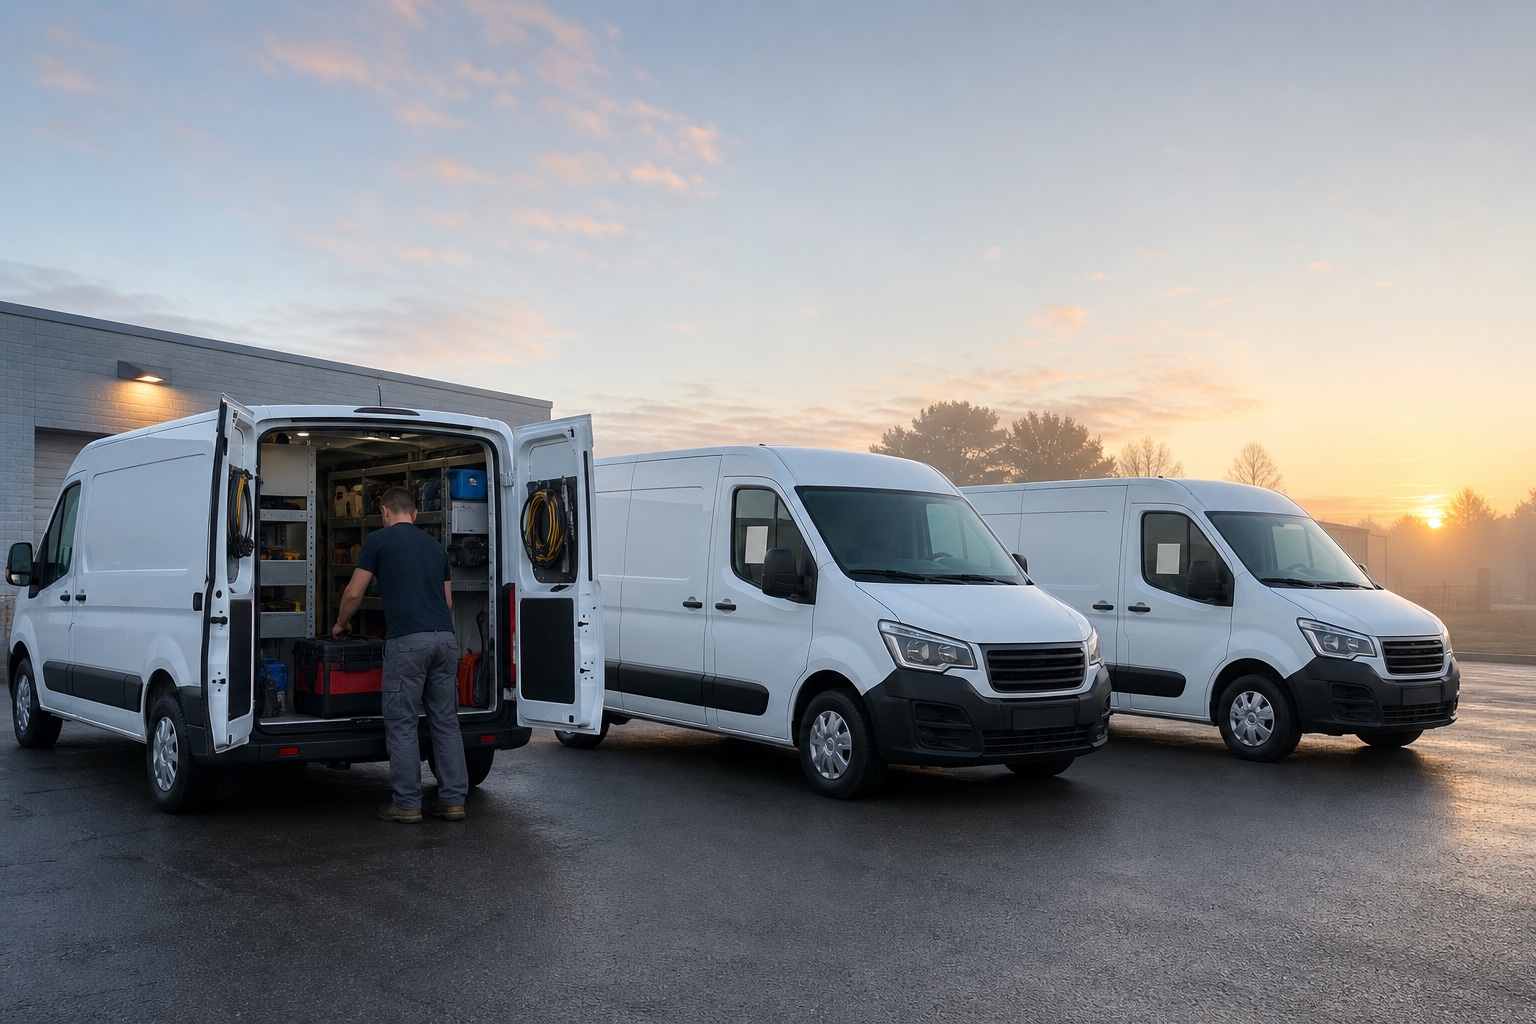
Most owners of service businesses hit the capital question at a specific moment. The fleet needs five more trucks. A competitor's book of business is for sale. A second branch makes sense on paper but not in the bank account. Payroll grows faster than collections every busy season.
The instinct is to search for investors. In the lower middle market, that is usually the wrong first move. Service businesses have better options, and the right one depends on what the money is for and how much control you want to keep.
The use picks the source more often than the other way around.
For a profitable service business, debt is almost always cheaper than equity. A loan costs interest. An investor costs a share of everything you build from here on.
SBA 7(a) loans run up to $5M and fund acquisitions, equipment, and expansion with less collateral than conventional loans require. Banks underwriting a service business want clean financials, consistent cash flow, and reasonable owner compensation. If your books cannot support a loan application today, fix that first. The same cleanup raises the value of the business when you eventually sell it.
Venture capital does not fund HVAC companies or pest control routes. That model needs businesses that can return a fund, and a service company with healthy margins and steady growth is a different kind of asset.
The equity buyers in this market are private equity firms, family offices, independent sponsors, and strategic acquirers. They rarely write a check for a small minority stake and walk away. They buy control, or a meaningful stake with a path to control, usually in businesses with $1M or more in EBITDA. If that describes your company, the conversation is less about raising capital and more about choosing a partner.
If the real goal is cash for the owner rather than cash for the business, the answer is not raising capital. It is a recapitalization: selling part of the company while keeping equity going forward.
A majority recap with rollover equity works like this. An owner sells 70% of a company at a $10M valuation and takes roughly $7M off the table. They keep 30% of the go-forward business and stay involved. If the new partner grows the company and sells it again in five or six years, that 30% can be worth a second meaningful payday. Owners who have done it call this the second bite of the apple.
This structure fits owners who are tired of carrying all the risk but not ready to leave. It is also the structure many buyers in home services actively prefer, because they want the operator who built the business to stay invested in it.
Two questions settle most of it. What is the money for, and how much control are you willing to trade? Equipment and working capital point to debt. Growth capital points to debt first and equity only at real scale. Owner liquidity points to a partial or full sale. Write down the use before you talk to anyone, because every capital provider will happily solve the problem they sell for.
GrowPCG is not a lender and not a broker-dealer, and we do not raise capital for businesses. We advise owners of founder-led service businesses on ownership transactions: full sales, recapitalizations, and the preparation that comes before either. If what you need is a loan, your bank and one competing bank are the right first calls.
If the question behind your capital search is really how to take money off the table without giving up the company you built, that is our lane. Request a consultation and we will walk through what a partial or full sale could look like for your business. If you are earlier in the process, start with our exit readiness guide.
Can GrowPCG raise capital or find investors for my business?
No. GrowPCG is an M&A advisory firm. We advise on sales and recapitalizations of founder-led service businesses. We do not place debt, raise funds, or sell securities.
What is a recapitalization?
A transaction where an owner sells part of the company, takes cash out, and keeps equity in the business going forward. Majority recaps sell control; minority recaps do not. In home services, majority recaps with rollover equity are the common structure.
Is debt or equity cheaper?
Debt, almost always, if cash flow supports the payments. Interest is a known cost. Equity gives away a share of all future value, which for a growing business is usually the more expensive trade.
When does selling a stake make sense?
When the owner wants liquidity, wants to reduce personal risk, or wants a partner with capital for acquisitions, and is willing to share control to get it. If none of those apply, debt or retained earnings are usually the better path.